

Top Tech Companies in Boston, MA (4,875)
Simply Business is the leading digital insurance marketplace dedicated to the success of small businesses. Our mission is to take the hassle out of buying insurance by offering simplicity, choice, and value to business owners. We connect our customers with top-rated insurers and policy recommendations tailored to their specific business needs and budget. We have nearly 20 years of experience supporting...
Simply Business's Top Stability & Growth Strengths
Strong Revenue Growth: Reporting indicates revenue increased in successive years, with UK results showing clear year-over-year gains and the parent highlighting category increases linked to the business. This pattern points to solid top-line momentum across core operations.
Profitability: Operating and post-tax profit improved materially, at times outpacing revenue growth. Such margin expansion suggests enhanced earning efficiency and disciplined execution.
Market Expansion: Customer reach advanced to a major UK milestone while U.S. distribution broadened through accelerated agent activity and additional channels. New insurer partnerships and digital launches further extend access to buyers.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating profitability is strengthening, with Q2 2026 delivering a 27% adjusted operating margin and 65% growth in adjusted diluted EPS. For 2025, operating income also rose to $1.7B, highlighting improved earnings leverage.
Resilient & Sustainable Growth: Gross profit increased every year from 2021 to 2025 and accelerated 25% year over year in Q2 2026. Management raised its 2026 gross-profit outlook to $12.51B (about 21% growth), reinforcing a multi-period expansion trend.
Cost & Operational Efficiency: Efficiency measures and AI-driven execution are associated with faster product delivery and improved profitability. Workforce streamlining and operating leverage supported margin expansion alongside growth in both Cash App and Square.

Arcadia is a leading healthcare data analytics platform that helps payers and providers turn complexdata into actionable insights. In turn, payers and providers can focus on what matters most — whether that’s patient outcomes, operational efficiencies, or financial performance. Arcadia partners with many of the nation’s top healthcare organizations and empowers its teams to drive real-world impact through innovation, collaboration,...

Arcadia's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A majority investment by Nordic Capital and a $125 million financing from Vista Credit Partners are described as fueling accelerated innovation and scale. These developments signal ample capital access to support ongoing expansion.
Product Line Growth: The CareJourney acquisition and subsequent launches of expanded suites (e.g., Ascent, CareJourney, LifeScience) and AI-enabled capabilities broaden the platform’s functionality. These moves indicate a deliberate build-out of offerings across providers, payers, and life sciences.
Market Expansion: New customer business reportedly added more than 2.25 million value-based lives and brought the ecosystem to over 170 million patient records, with the combined portfolio approaching 200 organizations. Active customer and partner engagement at Aggregate 2025 further suggests a deepening commercial footprint.
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is increasing at a double‑digit pace, with Q2 2026 revenue of about $1.91B up year over year. Full-year 2025 revenue also rose meaningfully to roughly $6.15B from $4.96B the prior year, indicating momentum across periods.
Profitability: Profitability is improving, as Q2 2026 net income increased to about $154M and operating income to roughly $152M from the prior year’s quarter. Recurring gross profit from subscription and fintech reached approximately $585M, showing stronger unit economics alongside scale.
Market Expansion: Customer reach is widening, with roughly 9,500 net locations added in Q2 2026 and total locations around 180,000, both higher than a year earlier. The company is also extending into retail, enterprise, international markets, and AI-enabled products such as Toast IQ.
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose 16% in 2025 and increased 14% year over year in Q2 2026, alongside gains in gross dollar volume, cross-border volume, and switched transactions. Feedback suggests this growth spans both the core network and international activity.
Profitability: Operating income and net income grew faster than revenue in Q2 2026 (operating income +17%, net income +19%), with full-year 2025 also showing double-digit profit increases. These results indicate operating leverage and earnings expansion alongside sales growth.
Diversified Revenue Streams: Value-added services and solutions grew roughly 18%–23% in recent periods and now comprise a substantial share of total revenue, including cybersecurity, fraud prevention, authentication, and analytics. This broadens the business beyond card transactions and supports continued expansion.
ASI is a dual-use software company that deploys predictive AI to the world's most complex operating environments. Backed by leading investors–including Andreessen Horowitz, Renegade Partners, and Spark Capital–we actively manage over 40% of all US air traffic across both public and private sector air operations. Partnering with major airlines like United and Alaska, we optimize thousands of flights daily, delivering...
Air Space Intelligence's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $325 million Series C at a reported $3 billion valuation, led by Spark Capital with participation from firms such as Andreessen Horowitz, signals strong capital access and confidence in future scale. The company describes using this capital to expand aviation, defense, energy, logistics, research, and engineering operations.
Market Expansion: Major awards like the FAA’s 12-year program (reported up to $875 million) and a five-year, $99 million U.S. Army contract, alongside airline customers and a National Grid collaboration, indicate expansion across government, commercial, and energy sectors. Partnerships such as Joby Aviation and new defense programs (e.g., DIU and the Open Mission Engine) further extend reach beyond the original aviation focus.
Strong Hiring & Retention: Dealroom reports 26.3% annual team growth with an estimated 173 employees and open positions, while another market source cites an increase from 163 to 228 in a quarter. Active recruiting across engineering, machine learning, cloud, mission operations, and growth roles points to organizational scaling.
Nasuni is a leading unstructured data platform for enterprises where file data is mission-critical for both people and AI. We power the operational file layer where work happens — helping organizations manage, protect, and activate data so teams can work smarter, reduce costs, and operate securely without limits. Built on a patented architecture that fuses cloud object storage with enterprise...

Nasuni's Top Stability & Growth Strengths
Strong Revenue Growth: Company-reported results indicate double-digit revenue growth in FY 2024 and continued expansion in recurring revenue. Feedback suggests growth is broad-based, spanning new customer wins and increased usage.
Profitability: Operating updates describe the business as profitable and cash-flow positive while scaling. This combination points to growth supported by financial discipline rather than spend-at-all-costs expansion.
Customer Loyalty & Retention: Account activity shows widespread expansions across the installed base alongside high retention. Feedback suggests the land-and-expand motion is a meaningful contributor to durable growth.
Catalant, the pioneer of Consulting 2.0, has helped the biggest and best companies use independent consultants for their most important work for over 10 years. More than 30% of the Fortune 500, top PE firms, and leading consultancies partner with Catalant to gain access to highly skilled, experienced business professionals who’ve solved their exact problems before. Over 100k talented independent...

Catalant Technologies's Top Stability & Growth Strengths
Strong Hiring & Retention: Employee headcount is observed to have risen from roughly 134 in 2023 to about 176 by early 2026, indicating active team expansion. Leadership additions in 2026 were framed as investments to support growth across priority industries.
Innovation-Driven Growth: New AI-focused services, including the Forward Deployed Experts offering, signal investment in turning AI strategy into execution. Company materials also highlight rising AI priority in client conversations, pointing to technology-led expansion.
Future-Ready Strategy: Recent senior appointments—including a new CFO and multiple leadership roles—are described as building the financial and organizational infrastructure to scale. Partnerships and continued enterprise focus suggest preparation for broader expansion.
Tufin is a world leading network security policy management company, managing and automating security changes across next gen firewalls and network devices. We are a hybrid technology, supporting on/off prem and cloud services. The automation orchestration piece is what sets us apart in the market, as this allows us to help our customers to implement their security changes in hours...
Tufin's Top Stability & Growth Strengths
Strong Revenue Growth: Company disclosures indicate double-digit revenue growth in 2024 and continued momentum via 30% year-over-year new-business growth in 2025. Reported 107% net retention further supports expansion of recurring revenue within the existing base.
Market Expansion: Reported 2.5× growth in cloud, SASE, and microsegmentation in 2025 points to traction beyond traditional network-policy management. Ongoing AI-driven launches and partnerships in 2025–2026 reinforce expansion into adjacent markets.
Customer Loyalty & Retention: A 2025 customer net retention rate of 107% suggests existing accounts expanded their spend after churn and contractions were accounted for. An NPS of 71, up sharply year over year, indicates rising advocacy alongside retention.


Ellevation is a mission-driven company dedicated to helping English Learners (ELs) achieve their highest aspirations. We are an indispensable partner to school district administrators, teachers and students across the United States, who use our products to manage complex program requirements, build the capacity of teachers to serve multilingual learners, and empower students with the academic language necessary for success in...
Ellevation Education's Top Stability & Growth Strengths
Market Expansion: Customer reach is described as rising from about 1,100 districts in 2021 to more than 1,900, with coverage across 50+ states and 2.5 million+ learners. Feedback suggests this broadened footprint indicates ongoing expansion in its core K–12 niche.
Product Line Growth: The launch of Ellevation Benchmark in January 2026 and added analytics/compliance capabilities extend the platform beyond program management into assessment and integrated workflows. Feedback suggests this creates opportunities to deepen adoption within existing districts and attract new ones.
Investor Backing & Capital Strength: Ownership by Curriculum Associates since 2021 is presented as adding financial, operational, and distribution support. Feedback suggests this backing underpins continued investment in hiring, product development, and commercial roles.
Robin is the leading AI platform for workplace operations. Since 2014, we’ve empowered people to do their best work by building tech solutions that fuel vibrant workplace experiences - allowing you to plan, manage and use your office in an intelligent way. With the leading desk and room booking software, the industry's first AI agent and our powerful workplace analytics,...
Robin's Top Stability & Growth Strengths
Innovation-Driven Growth: Product capabilities are expanding with new AI-powered Workplace Services and a Claude integration, signaling continued investment in advanced functionality. These launches move the platform beyond basic booking into orchestration and planning.
Strategic Partnerships: Availability of the One Workplace Platform through Google Cloud Marketplace provides an enterprise procurement path that can ease adoption. This distribution channel adds a route to incremental sales opportunities.
Strong Market Position & Advantage: Being named a Leader in Gartner’s 2026 Magic Quadrant for Workplace Experience Applications indicates competitive strength in the category. This recognition supports credibility with enterprise buyers.

We help customers of all sizes transform into true DevOps organizations. We've taken several customers from deploying applications once a month to hundreds of times a day. We're a team of experienced ServiceNow Wizards and passionate SRE's contributing to the open-source community, who have built multiple enterprise-scale CI/CD pipelines and integrations to help your organization build velocity in your release...

RapDev's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as up 54% over two years, with inclusion on the Inc. 5000 and the Financial Times’ Americas’ Fastest-Growing Companies list reinforcing multi‑year expansion. These signals point to sustained commercial momentum.
Strong Hiring & Retention: Headcount reportedly expanded from about 35 in 2021 to roughly 160–175 in 2026, alongside a 48% year‑over‑year hiring increase, indicating scaled delivery capacity. Active recruitment across engineering and operations further suggests continued team growth.
Market Expansion: The company extended its footprint into EMEA (2023) and APAC (2026), beginning with hires in Australia. International hiring indicates access to new markets and service opportunities.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Strong Revenue Growth: Square’s segment revenue increased 10% in 2025 and rose 16% year over year in Q2 2026, pointing to renewed topline momentum. These gains accompany rising seller activity and broader ecosystem adoption.
Profitability: Gross profit reached about $1.16 billion in Q2 2026, up 13% year over year, after a 9% increase for full-year 2025. The trend indicates improving economic contribution from processing, software, and financial services.
Market Expansion: International GPV grew 28% year over year in Q2 2026 while U.S. GPV rose 10%, alongside traction with larger merchants and vertical solutions such as restaurants and banking. These patterns suggest widening geographic and segment reach.
Flywire is a global payments enablement and software company. We combine our proprietary global payments network, next-gen payments platform and vertical-specific software to deliver the most important and complex payments for our clients and their customers.
Flywire's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue up 27.2% year over year in Q2 2026, with full-year 2025 revenue rising 26.6% to $623 million. Management also raised its 2026 growth outlook, reinforcing the trajectory.
Market Expansion: Client additions of 200+ across 45 countries in both Q1 and Q2 2026 and growth beyond education into travel, healthcare, and B2B indicate a broadening footprint. Education revenue outside core markets growing 30%+ further supports geographic expansion.
Profitability: Adjusted EBITDA increased 44.5% in Q2 2026 with margin expansion, and full-year 2025 reported positive net income. These trends suggest improving earnings power alongside scale.
Liberty Mutual Insurance exists to help people embrace today and confidently pursue tomorrow. A Fortune 100 company and global leader in property and casualty insurance, we’ve spent over a century creating innovative products, services and technologies to meet the world’s ever-changing needs and make a difference for our customers and communities.
Liberty Mutual Insurance's Top Stability & Growth Strengths
Profitability: Profitability is improving markedly, with net income and underwriting results rising and a strong combined ratio in early 2026. Lower catastrophe losses and stronger investment income also supported these gains.
Investor Backing & Capital Strength: Capital strength is solidifying as equity increased and S&P upgraded core operating companies’ financial strength ratings to A+, citing improved underwriting and capitalization. This positions the company to pursue growth from a stronger balance sheet.
Future-Ready Strategy: Strategy is shifting from “fixing” to “building,” emphasizing selective, profitability-threshold growth in segments showing momentum like Global Risk Solutions. Management highlights disciplined expansion rather than growth at any cost.
.png)
Charted clears the path for finance teams with AP Automation solutions built directly into your NetSuite environment—no integrations, no extra systems. Gain real-time clarity on every invoice, approval, and payment so you can focus on what really matters. Eliminate manual data entry with AI-powered capabilities and expense accrual automation to accelerate your month-end close. Combine the power of your full...
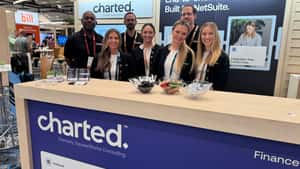
Charted, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Reported three-year revenue growth of 208% (2026 Inc. 5000) and 517% (2025 Deloitte Technology Fast 500), alongside consecutive appearances on major growth rankings, indicate substantial expansion. The company also improved its Inc. 5000 rank year over year, reinforcing continued momentum.
Market Expansion: A UK presence launched in January 2026 to serve the UK and EMEA, with subsequent rollouts of localized e‑invoicing across multiple European countries, point to expanding geographic reach. Announcements describe increasing international focus and operations.
Product Line Growth: New and expanded offerings such as AI‑driven invoice processing, Touchless Invoice Processing, International Payments, and broader e‑invoicing coverage reflect ongoing extension of the AP‑automation suite. Feedback suggests increasing product usage, with invoice scans rising from 1.80M (2023) to 2.69M (2024) and surpassing 3.36M by early December 2025.
Formation Bio is a tech-driven pharma company differentiated by radically more efficient drug development. Formation Bio has built a technology platform that optimizes all aspects of drug development, enabling more efficient trial design, faster trial completion, and higher quality trial data capture. Formation Bio acquires clinical-stage drugs from pharma and biotech and develops them faster and more efficiently, unlocking greater...

Formation Bio's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raising includes a $372 million Series D in 2024 with participation from Sanofi, bringing total funding above $600 million. The stated use of proceeds was to expand the drug pipeline and AI platform, indicating a strong financial base for growth.
Product Line Growth: The portfolio has expanded through multiple in-licensing deals in 2025–2026 and now spans preclinical, Phase 1, and Phase 2 programs. Tangible execution includes dosing the first participant in the BLKR201 Phase 1 trial in June 2026, only months after licensing the asset.
Strategic Partnerships: High-profile collaborations include work with Sanofi and OpenAI to build AI tools for drug development, alongside a Sanofi licensing agreement for gusacitinib with significant potential milestone value. These relationships reinforce external validation and create pathways to scale development.
It's simple, at DraftKings, we believe life is more fun when you're in on the action. For that reason, we’re committed to responsibly creating the world’s favorite games and betting experiences. We’re developing the most innovative and entertaining real money products and offers; to forever transform how people experience sports; to be a fully vertically integrated sports betting operator. It's...

DraftKings's Top Stability & Growth Strengths
Strong Revenue Growth: Annual revenue rose from $3.67B in 2023 to $6.05B in 2025, and management guides to $6.5–$6.9B for 2026. This multi-year trajectory signals substantial top-line expansion despite quarterly volatility.
Market Expansion: The sportsbook operates in 30 states, Washington, D.C., Puerto Rico, and parts of Canada. Broader geographic access supports continued user and wagering growth.
Diversified Revenue Streams: Sportsbook, iGaming, and the newer Predictions offering provide multiple growth avenues. iGaming revenue grew 7.5% year over year in Q2 2026, while Predictions launched in December 2025 as another channel.
Blink is the mobile-first employee experience platform that connects your people, systems, and culture in one super-app. It bridges the digital divide between deskless and desk-based workers, supercharging employee communication and engagement at industry-leading companies like McDonald's, Nokia, Domino’s, JD Sports, RATP Dev, and Stagecoach. Blink is the top-rated Employee Communications Application on Gartner Peer Insights and a Leader in...

Blink - The Employee App's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $17 million investment in May 2026 from Enlightened Hospitality Investments signals strong financial support for scaling product and market reach. A documented multi-round funding history further reinforces access to capital for growth.
Strategic Partnerships: A global partnership with Shake Shack and a large-scale rollout at JD Group highlight the ability to win and expand enterprise relationships. Placement as a Workday Ventures portfolio company underscores ecosystem alignment that can accelerate distribution.
Market Expansion: Reported additions of over 700,000 hospitality users in 2025 and new international deployments point to widening geographic and vertical reach. Enterprise wins across retail, hospitality, transportation, and healthcare indicate momentum beyond a single sector.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...

Nexthink's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have more than tripled between 2021 and 2025 while profitability improved. AI-related ARR also rose from $20 million in Q1 2025 to $109 million in Q1 2026, reinforcing momentum.
Market Expansion: Reported enterprise customers grew from 1,200+ in 2024 to 1,500+ in 2025, and platform reach expanded from 15 million to 25 million endpoints/employees. International moves, including plans for Japan and South America, indicate continued geographic expansion.
Investor Backing & Capital Strength: A majority investment by Vista Equity Partners at an approximately $3 billion valuation in 2025 signals strong external confidence. This transaction follows years of scaling and provides capital support for the next phase.



