Top E-commerce Companies in Boston, MA (138)
.png)
Klaviyo (NYSE: KVYO) is the B2C CRM. Powered by its built-in data platform and AI, Klaviyo combines marketing automation, analytics, and customer service into one unified solution, making it easy for businesses to know their customers and grow faster. Klaviyo (CLAY-vee-oh) helps over 183,000 brands like Mattel, Glossier, Daily Harvest, and Liquid Death deliver 1:1 experiences at scale, improve efficiency,...
Klaviyo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding with consecutive year-over-year increases in the first half of 2026 and management raising the full‑year outlook. The quarter ended June 30, 2026 also closed at nearly a $1.5 billion annualized run rate.
Profitability: Margins and cash generation are improving, with recent quarters showing positive non‑GAAP operating income and strong free cash flow. Materials also highlight operating discipline alongside growth.
Market Expansion: International revenue is outpacing the Americas, supported by new regional hubs such as Dublin and Singapore. Rising adoption of additional channels (e.g., SMS/WhatsApp) and larger‑account wins indicate a broader addressable market.
Who We Are Chewy is where pet parents find everything they need for life with pets, from food to fun to pharmacy. We make pet care easier, more informed, and more joyful through fast, reliable delivery and award-winning 24/7 Customer Care, including access to pet health support when it’s needed. Founded in 2011, Chewy combines the convenience of online shopping with...

Chewy's Top Stability & Growth Strengths
Profitability: Margins and earnings are expanding, with Q1 FY2026 adjusted EBITDA up, gross margin at 30.1%, and positive net income. FY2025 also delivered record free cash flow alongside margin expansion.
Customer Loyalty & Retention: Autoship represents a large, recurring base at 84.4% of Q1 FY2026 net sales, growing at a double‑digit pace. Rising net sales per active customer and cross‑category engagement point to stickier spend and retention.
Diversified Revenue Streams: Pet health services are scaling through SmartPak and the Modern Animal acquisition, complementing core e‑commerce with clinics and pharmacy. The Modern Animal deal is expected to add over $125M in annualized run‑rate revenue and expand clinics from 18 to 47, with additional openings planned in FY2026.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Record adjusted operating income and margin accompanied the growth, with management lifting 2026 adjusted operating income guidance to a higher margin level. Operating leverage was emphasized alongside strong second‑quarter results.
Resilient & Sustainable Growth: Gross profit accelerated year over year into Q2 2026 (after an even stronger Q1), and full‑year 2026 gross profit guidance was raised meaningfully. Leadership framed gross profit as the clearer indicator of underlying momentum given revenue mix effects.
Cost & Operational Efficiency: Efficiency measures, including running a leaner organization, boosted margins and contributed to record profitability. Leaders also pointed to continued strength into the second half with healthy monetization and risk metrics, indicating efficient scaling.
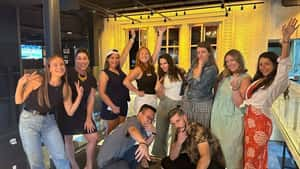
LogicManager believes performance is a result of effective risk management. Our ERM software and top-rated customer experience help organizations manage surprises before they happen - ensuring a positive impact on the organization and community at large. But don’t just take our word for it; we're proud to be a certified Great Place to Work® every year since 2017!
LogicManager's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Ongoing product marketing, maintained presence in analyst/buyer venues, and newly updated customer stories indicate continued operations with steady momentum into 2025–2026. Headcount and hiring signals point to measured expansion rather than a rapid ramp, aligning with a sustainability-oriented trajectory.
Innovation-Driven Growth: Enhancements such as LM 2.0, new AI capabilities like Risk Ripple Analytics, and a 2025 Connector Program demonstrate active product investment. Workshops and launches in 2026 further underscore forward-leaning roadmap execution.
Healthy Cash Flow: A bootstrapped model with no outside funding disclosed and indications of cash‑flow positivity suggest disciplined, cash-generating operations. This supports ongoing product and go‑to‑market activity without reliance on external capital.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Square gross profit and payment volumes are rising with signs of acceleration in 2026; Q2 2026 gross profit reached about $1.16B and GPV increased at a low‑teens rate year over year. Management also raised the full‑year outlook at the Block level, indicating momentum in which Square is contributing.
Market Expansion: Traction with larger, multi‑location sellers and strong international GPV growth indicate expansion beyond very small businesses. U.S. GPV also accelerated to its strongest pace since Q2 2023, complementing faster non‑U.S. growth.
Innovation-Driven Growth: Hardware and AI are highlighted as fast‑compounding capabilities, and Square Financial Services has begun processing acquiring volume. An expanded ISO and partner ecosystem is bringing in more new sellers and deepening product adoption.
Since 2012, Mirakl has been pioneering the platform economy, empowering retail and B2B enterprises with the most advanced, secure and scalable technology to digitize and expand product assortment through marketplace and dropship, improve efficiency in supplier catalog management and payments, personalize shopping experiences, and boost profits through retail media. Mirakl is trusted by Macy’s, Saks, Henry Schein, The Knot, 1800-Flowers, Best...

Mirakl's Top Stability & Growth Strengths
Profitability: The company achieved full-year profitability at the group level in 2025, building on earlier platform-level profitability. This indicates improving operating leverage alongside growth.
Strong Revenue Growth: Annual recurring revenue rose to $218M in 2025 from $177M in 2024, showing renewed momentum versus the prior year. This expansion is supported by additional large-enterprise customer wins and bookings growth.
Diversified Revenue Streams: Newer offerings are contributing incremental monetization, with Mirakl Connect generating ARR and Mirakl Ads seeing rising ad spend and client additions. The expanding seller network and the launch of Nexus further broaden potential revenue sources.

Akeneo is the Product Experience (PX) company and global leader in agentic-first Product Cloud solutions, providing the foundational operating system for the AI-powered commerce era. With its Product Cloud, Akeneo enables brands, manufacturers, distributors, and retailers to centralize, govern, and orchestrate their product information, transforming fragmented data into trusted, actionable assets. With the integration of PricingHUB, Akeneo extends its platform...

Akeneo's Top Stability & Growth Strengths
Market Expansion: Public materials indicate customer counts rising from 500+ in 2021 to more than 1,000 by mid‑2025, suggesting steady adoption. Partner motions such as becoming a Shopify Premium Partner in 2025 further extend reach and implementation capacity.
Product Line Growth: Acquisitions of Unifai (2023) and PricingHUB (2026) expand the Product Cloud from core PIM/PXM into AI‑driven enrichment and pricing, broadening wallet share opportunities. A continued 2025–2026 release cadence (e.g., AI agents, CDN, data architect enhancements) reinforces an expanding offering.
Investor Backing & Capital Strength: A $135M Series D in March 2022 underpins subsequent platform launches and acquisitions, signaling capacity to execute on product and international initiatives. This capital base supports measured expansion.
Ahold Delhaize USA, a division of global food retailer Ahold Delhaize, is part of the U.S. family of brands, which includes five leading omnichannel grocery brands – Food Lion, Giant Food, The GIANT Company, Hannaford and Stop & Shop. Our associates support the brands with a wide range of services, including Finance, Legal, Sustainability, Commercial, Digital and E-commerce, Technology and...
Ahold Delhaize USA's Top Stability & Growth Strengths
Innovation-Driven Growth: U.S. online sales are expanding at sustained double-digit rates (+14.3% in Q1 and +14.5% in Q2 2026), supported by the completed PRISM omnichannel platform and the rollout of the Edge retail media offering. E‑commerce profitability in 2025 and ongoing AI/automation initiatives further reinforce a tech-enabled growth flywheel.
Future-Ready Strategy: The company is investing for long-term growth through an $860 million North Carolina distribution center, a multi‑year $1 billion U.S. price‑investment program, and accelerated remodels/new stores. Targets to lift omnichannel loyalty penetration and app usage by 2028 and a push toward 45% private‑label penetration underscore forward-leaning execution.
Resilient & Sustainable Growth: U.S. comparable sales remained positive in 2026 to date (+1.5% in Q1; +0.8% in Q2), and management reiterated full‑year 2026 guidance after both quarters. Market‑share gains across most U.S. brands were noted even as group net sales growth was modest (+1.9% at constant rates in Q2).
Babylist is the trusted platform for millions of growing families. For over a decade, Babylist has been the technology solution for expecting parents and the community that supports them, expanding from baby registry into a full-service platform that helps parents make decisions with confidence, stay connected, and build happy and healthy families. Every year Babylist helps over 9M people make...
Babylist's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have surpassed $750 million in 2025, with coverage indicating sales could approach $1 billion in 2026. Company materials also cite more than $1.4 billion in GMV and over 10 million shoppers, underscoring momentum.
Profitability: The company notes its eighth consecutive profitable year in 2025, suggesting durable unit economics alongside scale. Statements also indicate margin improvement while expanding across commerce, health, and media.
Diversified Revenue Streams: Growth is spreading beyond the core registry, with Health and Media highlighted as expanding and acquisitions (SourceMD, Expectful) broadening monetization. New formats such as showrooms and financial tools further extend revenue opportunities.

At Bose Corporation, we’re powered by our legendary brands — Bose, McIntosh, and Sonus faber — bringing together more than 175 years of combined technical expertise, craftsmanship and artistry. Founded by Dr. Amar Bose, our company is driven by purpose and devoted to advancing what’s possible in audio — creating transformative experiences in the home, on the go, and on...

Bose's Top Stability & Growth Strengths
Product Line Growth: Second‑generation QuietComfort Ultra earbuds (June 2025) and headphones (September 2025), alongside the 2026 Lifestyle Collection for home audio, show an active refresh of flagship and adjacent categories. This cadence supports relevance in premium ANC and home audio segments.
Strategic Partnerships: The June 9, 2026 acquisition of StreamUnlimited Engineering was framed to accelerate “Sound by Bose” licensing and expand streaming capabilities, signaling a platform and licensing push beyond hardware. Automotive/OEM integrations and third‑party “Sound by Bose” products provide scalable routes to broaden reach.
Strong Market Position & Advantage: An EU market study lists Bose among the top headphone brands by sales volume, indicating sustained demand in a major region. Continued momentum in ANC‑focused launches reinforces competitive standing at the premium end.
Headquartered in Boston, Massachusetts, CarGurus is the #1 visited digital auto platform in the U.S. for shopping, buying, and selling new and used vehicles and an award-winning place to work. We give drivers and dealers the confidence to buy or sell cars exactly how they want: online, in-person, or a combination of both. Our culture fosters kindness, collaboration, and innovation,...

CarGurus's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 13–15% year over year in Q1–Q2 2026, and guidance calls for full‑year 2026 growth of 10–13%, indicating sustained top‑line momentum.
Healthy Cash Flow: Operating cash flow of $94.6M and free cash flow of $87.7M in Q2 2026 point to solid cash generation that can support investment and capital returns.
Innovation-Driven Growth: AI‑driven dealer tools and a new consumer “Guru” layer are described as driving deeper engagement and higher monetization, alongside international growth.

Profitero+ is the leading digital commerce company, trusted by more than 4,000 brands worldwide. We help brands break down silos and turn data into decisive action through intelligence-driven, end-to-end solutions that unify media, content, operations and strategy. Powered by advanced AI, robust digital shelf analytics across 1,400+ retailers in 70 countries and unmatched expertise from digital commerce specialists in 15...

Profitero+'s Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent analyst recognition positions Profitero+ as a top-tier vendor in digital shelf analytics, reinforced by repeated “leader” framing and competitive shortlisting against major peers.
Investor Backing & Capital Strength: Ownership by Publicis Groupe is presented as providing significant resources and integration into a broader commerce and retail-media stack, supporting continued investment capacity and enterprise credibility.
Product Line Growth: The launch of Profitero+ as a broader integrated model combining technology with managed services signals expansion beyond analytics into more end-to-end execution across media, content, operations, and strategy.
_0.jpg)
Saks is a world-renowned luxury ecommerce destination. The company’s unique approach combines a focus on the digital customer experience with a strong connection to a network of extraordinary stores that extends that seamless experience into the real world. On its website and app, Saks offers an unparalleled selection of curated merchandise across fashion for women and men, beauty, jewelry, home décor...


Smilo caters to millennial parents with a direct-to-consumer website that offers high-performance products for babies and children. With backgrounds ranging from biomedical engineering to pediatric dentistry, Smilo's team members have leveraged their collective experience to create products like pacifiers, baby blankets and more.


Trellis helps Amazon and Walmart eCommerce sellers grow their business with the first of its kind, eCommerce Merchandising platform built on the 4Ps framework. Through the lens of Price, Product, Placement, and Promotion, let's find out your Return on Merchandising Spend (ROMS).

TJX is the leading off-price apparel and home fashions retailer in the U.S. and worldwide, with four global home offices, seven brands, nearly 4,700 stores in nine countries, and five distinctive branded e-commerce sites. As Associates, we make a difference with our contributions—collaborating in delighting shoppers with hidden treasures.
The TJX Companies, Inc.'s Top Stability & Growth Strengths
Strong Market Position & Advantage: Evidence indicates TJX is the leading off-price retailer globally, with the largest U.S. off-price chains and a multi-banner footprint that reinforces scale advantages. Company statements and industry coverage cite sustained share gains and a hard-to-replicate model.
Strong Revenue Growth: Recent disclosures show rising net sales, higher comparable sales, expanding pretax margins, and materially higher EPS, alongside raised full-year guidance. Management also highlights a long record of steady sales and earnings growth across varied environments.
Market Expansion: The store fleet surpassed 5,000 locations with ongoing openings across banners and countries, and management targets approximately 7,000 over time including new markets like Spain. Active hiring and thousands of open roles align with continued scaling of operations.

Gopuff is the go-to solution for immediate everyday needs, fulfilling customer orders of cleaning and home products, over-the-counter medications, baby and pet products, food and drinks, and in some markets, alcohol – in just minutes. With micro-fulfillment centers in every market it serves, the company delivers thousands of products quickly for a flat $2.95 delivery charge. Gopuff is open 24/7...

Gopuff's Top Stability & Growth Strengths
Strong Market Position & Advantage: Gopuff is presented as the de facto leader in U.S. first‑party instant‑needs delivery, operating roughly 460 micro‑fulfillment centers as of June 2026. Its vertically integrated model supports fast promise times and reinforces a defensible position within this niche even as broader convenience leadership is more contested.
Investor Backing & Capital Strength: The company raised $250 million in November 2025, with materials citing record revenue and contribution profit alongside its “strongest financial position.” This financing creates room to invest in AI, consumer experience, and infrastructure while pursuing disciplined expansion.
Strategic Partnerships: Partnerships with Amazon in the U.K., Disney for shoppable CTV, and GrowthLoop for retail media expand reach and monetization levers beyond the core app. Additional integrations like SNAP/EBT acceptance and Uber Eats distribution widen access to value‑focused shoppers.

Invaluable is the world’s leading online marketplace for fine art, antiques and collectibles. Working with more than 4,000 of the world’s premier auction houses, dealers and galleries, Invaluable helps buyers from 200 countries connect with the things they love. With best-in-class online bidding technology, along with a fixed-price retail platform, Invaluable provides sellers with e-commerce and marketing solutions, as well...

.png)
HelloFresh is on a mission to change the way people eat, forever! From our 2011 founding in Europe’s vibrant tech hub Berlin, we’re evolving from the world’s leading meal kit company to the world's leading food solutions group. We delivered 227 million meals and reached 6.94 million active customers around the world in Q3 2021. HelloFresh Group consists of six brands...

HelloFresh's Top Stability & Growth Strengths
Strong Market Position & Advantage: Evidence indicates HelloFresh is widely regarded as the global market leader in meal kits by revenue, scale, and multi‑country footprint, particularly across North America and Europe. Consolidation in the U.S. (e.g., Blue Apron’s sale) has further concentrated share among scaled players like HelloFresh.
Profitability: Company communications highlight a pivot to higher‑value customers, positive adjusted EBITDA in FY 2025, and positive free cash flow in early 2026, signaling disciplined margin focus. Management emphasizes profitability before volume, with ongoing execution and cash generation programs.
Diversified Revenue Streams: A multi‑brand portfolio spanning cook‑and‑eat and ready‑to‑eat (Factor) across roughly 18 countries broadens price points and meal formats. Non‑U.S. RTE showed double‑digit growth, and new capacity (e.g., a Factor Europe facility in Germany) supports the category.