

Top Payments Companies in Boston, MA (51)
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose 14% year over year in Q2 2026 (12% currency‑neutral) to $9.3B, with first‑half 2026 up 15% and full‑year 2025 up 16% (15% currency‑neutral). These results indicate sustained top‑line momentum across recent periods.
Diversified Revenue Streams: Value‑Added Services & Solutions grew 20% in Q2 2026 (18% currency‑neutral) and 23% in 2025, outpacing Payment Network growth. This mix shift adds a faster‑growing second engine alongside the core network.
Resilient & Sustainable Growth: Transaction fundamentals remained healthy in Q2 2026—gross dollar volume +8% to $2.9T, cross‑border +12%, and switched transactions +9% (local‑currency). Multi‑year growth from 2025 into the first half of 2026 underscores durable momentum.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Record adjusted operating income and margin accompanied the growth, with management lifting 2026 adjusted operating income guidance to a higher margin level. Operating leverage was emphasized alongside strong second‑quarter results.
Resilient & Sustainable Growth: Gross profit accelerated year over year into Q2 2026 (after an even stronger Q1), and full‑year 2026 gross profit guidance was raised meaningfully. Leadership framed gross profit as the clearer indicator of underlying momentum given revenue mix effects.
Cost & Operational Efficiency: Efficiency measures, including running a leaner organization, boosted margins and contributed to record profitability. Leaders also pointed to continued strength into the second half with healthy monetization and risk metrics, indicating efficient scaling.
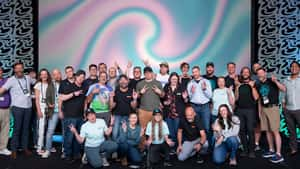
Moov is a payments infrastructure platform making it easy to accept, store, send, and spend money all from a single, elegantly-designed API. Instead of stitching together multiple vendors, software companies simply add Moov to their products to get the latest in payment technology, user onboarding, licensing, compliance, and more.
Moov's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with Jack Henry for Visa Direct enablement and integrations like LoanPro’s native Moov processor (June 2026) point to expanding distribution and credibility with financial institutions and lenders. Additional ecosystem ties (e.g., Plaid, Currencycloud, Google Cloud Marketplace) reinforce growing channel reach and capability breadth.
Innovation-Driven Growth: Ongoing 2026 documentation and dashboard updates—covering instant-rail support (RTP/FedNow), new partner billing features, surcharging, and versioned API releases—indicate sustained product velocity. Becoming a licensed card/acquiring processor and highlighting a Visa processing relationship in 2024 suggest broadening use cases over subsequent years.
Market Expansion: Operating fintechdevcon (listed as organizer in 2025–2027) expands developer and partner pipelines that often precede commercial wins. New integrations and ecosystem activity through 2025–2026 signal growing platform adoption beyond initial beachheads.
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Q2 2026 total net revenue rose 4% sequentially to $15.9 billion. Integration of Discover and Brex contributed to higher non‑interest income and broader payments capabilities.
Profitability: Q2 2026 net income reached $3.0 billion, up from $2.2 billion in Q1 2026, alongside a net interest margin of 8.01%. Management also cited strong credit performance, including a $662 million reserve release.
Market Expansion: Acquisition‑driven scale is broadening reach, with the Discover deal (closed May 18, 2025) and Brex (closed April 7, 2026) adding network and corporate card/spend‑management capabilities. Balance‑sheet growth continued in Q2 2026 as period‑end loans rose 2% to $457.2 billion and total assets reached $673.8 billion.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Square gross profit and payment volumes are rising with signs of acceleration in 2026; Q2 2026 gross profit reached about $1.16B and GPV increased at a low‑teens rate year over year. Management also raised the full‑year outlook at the Block level, indicating momentum in which Square is contributing.
Market Expansion: Traction with larger, multi‑location sellers and strong international GPV growth indicate expansion beyond very small businesses. U.S. GPV also accelerated to its strongest pace since Q2 2023, complementing faster non‑U.S. growth.
Innovation-Driven Growth: Hardware and AI are highlighted as fast‑compounding capabilities, and Square Financial Services has begun processing acquiring volume. An expanded ISO and partner ecosystem is bringing in more new sellers and deepening product adoption.
.jpg)
Founded in 2002, Leader Bank is a Massachusetts-based entrepreneurial financial institution that approaches banking differently. The core tenets of Leader Bank include client services, exemplary products, and innovation to meet the needs of its clients. Leader Bank’s best-in-class staff has been at the forefront of supporting the bank’s rapid growth and client-oriented solutions, as the bank has continued to expand...

Leader Bank's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Total assets have climbed from about $4.6B at year‑end 2024 to roughly $5.28B by Q2 2026, extending a multi‑year rise noted in the bank’s own reports. Regulatory snapshots in 2025–2026 align around $5.0B+ in assets, indicating continued balance‑sheet expansion.
Market Expansion: Branch additions in 2026 (Boston Seaport/Back Bay, Andover, Falmouth) and the launch of new teams, including a nationwide SBA group and a West Coast deposit team, point to active geographic and channel growth. Leadership has framed these moves as organic expansion amid broader industry consolidation, with the Falmouth opening publicized.
Strong Market Position & Advantage: In Massachusetts home‑purchase mortgages, the institution is cited as the top bank lender for 2025 by both dollar volume and loan count. A June 2026 HMDA‑based composite also ranked it first overall in the state, signaling durable competitive strength in this niche.
Flywire is a global payments enablement and software company. We combine our proprietary global payments network, next-gen payments platform and vertical-specific software to deliver the most important and complex payments for our clients and their customers.
Flywire's Top Stability & Growth Strengths
Strong Revenue Growth: Recent quarters and the FY2025 comparison show sustained double‑digit top‑line increases alongside robust gains in payment volume. Guidance was raised for FY2026, reinforcing expectations for continued expansion.
Profitability: Adjusted EBITDA and margins expanded while the company achieved GAAP profitability in FY2025 and posted a profitable first quarter in 2026. Management also points to further margin expansion for FY2026.
Market Expansion: Hundreds of new client wins and marquee enterprise deals were highlighted across regions, with momentum spanning education software, travel/hospitality, and B2B. The enlarging client footprint aligns with upgraded growth targets.
Coupa is a global technology company that helps businesses run smarter by connecting all the ways they spend money — from procurement and expenses to payments and supply chain decisions — in one intelligent platform. In simple terms, Coupa gives organizations the visibility and control they need to make better financial choices, reduce waste, and drive real impact. It’s where...
Coupa's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results highlight the highest revenue quarter in company history in Q4 FY26. Earlier updates cited over $1B in FY2024 billings alongside hundreds of new customers, indicating commercial momentum post–take‑private.
Innovation-Driven Growth: Adoption of Coupa Navi AI agents and acquisitions such as Rossum and Tonkean are aimed at accelerating autonomous spend management and AI-driven intake/orchestration. Independent event coverage described a coherent roadmap centered on a network-led, autonomous spend vision.
Strategic Partnerships: A five‑year strategic collaboration agreement with AWS was announced in 2026. This alliance is positioned to accelerate AI-driven capabilities and support expansion of the autonomous spend‑management vision.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.

Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue grew 31% to $702M in FY2026, then accelerated to 40% year over year in Q1 FY2027, with full‑year FY2027 revenue outlook raised to roughly 30% growth. Momentum is reinforced by expanding enterprise adoption and integrations that support usage growth.
Profitability: FY2026 marked the first full year with positive non‑GAAP operating income alongside positive operating and free cash flow, and Q1 FY2027 non‑GAAP operating margin reached 11%. These milestones indicate improving operating leverage as scale increases.
Cost & Operational Efficiency: AI agent automation (e.g., Ava handling about 52% of interactions in FY2026) is underpinning service scalability and margin expansion. Further increases in AI‑handled interactions are expected to support additional efficiency gains.

As part of the Central bank of the United States, the Boston Fed works to promote sound growth and financial stability in New England and the nation. We contribute to communities, the region, and the nation by conducting economic research, participating in monetary policy-making, supervising certain financial institutions, providing financial services and payments, playing a leadership role in the payments...
Federal Reserve Bank of Boston's Top Stability & Growth Strengths
Innovation-Driven Growth: The bank operates the FedNow Service for all Reserve Banks and co-led Project Hamilton with MIT, underscoring active leadership in instant payments and CBDC research. It also introduced the Weekly State-level Economic Conditions Index, expanding data and analytical capabilities.
Future-Ready Strategy: Capital investments were budgeted to roughly double in 2024 versus 2023 and rise again in 2025 plans, emphasizing stepped-up spending on facilities and technology. System priorities cite payments modernization (including FedNow, ISO 20022) and IT infrastructure as resource drivers.
Strategic Partnerships: Collaboration with MIT’s Digital Currency Initiative on Project Hamilton and formation of a First District Payments Advisory Council reflect deliberate external engagement to advance payments and research. Cross‑Reserve Bank roles, including operating FedNow, show coordinated partnerships that expand Boston’s operational scope.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Gross profit is rising rapidly, with Cash App up 31% year over year in Q2 2026 and companywide gross profit also expanding. Guidance was raised on the strength of Cash App and Square, underscoring ongoing profit momentum.
Cost & Operational Efficiency: Management is prioritizing gross profit per employee and operating margins, aiming to run a smaller company while continuing product and user growth. The February 2026 restructuring was framed around “disciplined growth” and AI‑driven efficiency.
Resilient & Sustainable Growth: Users and engagement are trending up, with about 59 million monthly actives at end‑2025 and accelerating inflows per active alongside rising “primary banking” usage. Momentum carried into 2026, with strong early‑year gross profit growth supporting raised full‑year outlook.
.png)
Charted clears the path for finance teams with AP Automation solutions built directly into your NetSuite environment—no integrations, no extra systems. Gain real-time clarity on every invoice, approval, and payment so you can focus on what really matters. Eliminate manual data entry with AI-powered capabilities and expense accrual automation to accelerate your month-end close. Combine the power of your full...
Charted, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: External growth lists (Deloitte Technology Fast 500 and Inc. 5000) and disclosed multi‑year gains indicate accelerating top‑line momentum. Consecutive placements and upward movement on these rankings reinforce the trajectory.
Market Expansion: A UK office launch to support UK/EMEA and the introduction of International Payments signal geographic expansion and a broader commercial footprint. The 2025 rebrand was framed as enabling a larger, global push for a NetSuite‑native platform.
Innovation-Driven Growth: Regular release trains (e.g., 2025.1/2025.2) and new capabilities such as Invoice AI, Touchless Invoice Processing, and planned e‑invoicing reflect sustained product investment. Compatibility updates tied to NetSuite versions point to a maturing, actively developed platform.

InvoiceCloud provides a complete, simple, and secure electronic bill presentment and payment solution. Our SaaS platform provides flexible and always-up-to-date online payment solutions that can be configured to meet the unique needs of your organization. And our simple-to-use interface engages customers throughout the payment process to deliver your highest ever e-payment adoption rates.
InvoiceCloud's Top Stability & Growth Strengths
Strong Market Position & Advantage: The company is often positioned as a leader in EBPP for utilities, government, and insurance, with awards and category recognition reinforcing its niche strength.
Market Expansion: Evidence points to expanding into insurance and government ecosystems, new geographies like India, and continued partner-led distribution growth.
Product Line Growth: Ongoing innovation is highlighted by AI-powered billing features, omnichannel capabilities, and numerous new integrations.

Centime is the leading cash management suite that helps fast-growing businesses easily control and manage cash flow. From forecasting, collections, invoicing, payments, credit, and reporting — our connected solutions leverage automation and artificial intelligence to help finance leaders increase productivity, reduce operational costs, and proactively manage risk. Centime is the only company to offer accounts payable, accounts receivable, and banking...

Blue Owl (NYSE: OWL) is a leading asset manager that is redefining alternatives®. With $235 billion in assets under management as of September 30, 2024, we invest across three multi-strategy platforms: Credit, GP Strategic Capital, and Real Estate. Anchored by a strong permanent capital base, we provide businesses with private capital solutions to drive long-term growth and offer institutional investors, individual...
Blue Owl Capital's Top Stability & Growth Strengths
Strong Market Position & Advantage: Blue Owl is recognized as a leader in scaled direct lending/private credit and GP-stakes, with capacity to anchor $1B+ financings and one of the largest BDC complexes. A roughly $315B AUM platform across Credit, Real Assets, and GP Strategic Capital reinforces top-tier positioning in its core niches.
Strong Revenue Growth: Revenue increased in 2025 and continued to grow in Q1 2026, alongside rising fee-related and distributable earnings. Reported momentum in recent quarters supports a strengthening top line.
Diversified Revenue Streams: Three scaled platforms and a large share of fee-paying, longer-duration capital diversify fee revenues beyond carry-dependent strategies. Continued fundraising and new strategy closes (e.g., secondaries and asset special opportunities) broaden sources of fees across the platform.

DipJar is changing the game of fundraising with a cashless donation jar and an integrated payments platform that enable joyful, engaging, and frictionless giving. With DipJar, organizations of any size can collect donations anywhere and Create More Giving Moments.
We build next-generation payment ramps for Web3 businesses. The C14 widget allows any user in our coverage areas to easily KYC, store payment methods, and transact across partner blockchain ecosystems with a seamless, e-commerce-like payment flow.

Osaic provides the support, resources, and community designed for the future of wealth management. Securities and investment advisory services are offered through the firms: Osaic Wealth, Inc., Osaic Institutions, Inc., Osaic FA, Inc., Osaic FS, Inc., and Triad Advisors, LLC, broker-dealers, registered investment advisers, and members of FINRA and SIPC. Securities are offered through Securities America, Inc., American Portfolios Financial Services,...
Osaic's Top Stability & Growth Strengths
Strong Market Position & Advantage: Scale and ranking are repeatedly highlighted, with about 11,000 financial professionals and $700B+ in assets under administration placing the firm among the largest independent wealth platforms. Leadership references include top-three revenue positioning and national reach across all 50 states.
Market Expansion: Ongoing acquisitions and advisor recruitment expand the footprint into banks, credit unions, independent advisors, and HNW RIA channels (e.g., Ladenburg, Infinex, American Portfolios, Lincoln Wealth, CW Advisors). Consolidation under a unified platform and continued affiliations signal sustained reach growth.
Investor Backing & Capital Strength: Backing from Reverence Capital and a January 2026 refinancing of $750 million to extend maturities and lower costs indicate available capital to support strategy. Ratings commentary notes stable outlooks and improving margins tied to scale and a fee‑only shift.

A UK company, Sun Life Financial of Canada is focused on building excellent customer service by offering the highest levels of customer care. We have been serving customers in the UK for over 100 years

HedgeServ is a leading global fund administrator with more than $450 billion in assets under administration across all investment vehicles including Hedge Funds, Private Equity Funds, UCITS, Hybrid Credit Managers, Funds of Funds and Managed Account Platforms. We optimize our clients’ experience using unique proprietary technology coupled with robotic process automation, intuitive digital programs powered by machine learning, and enhanced...
HedgeServ's Top Stability & Growth Strengths
Strong Market Position & Advantage: The firm is widely viewed as a top‑tier, independent alternative‑fund administrator with substantial AuA and a track record of category wins in marquee award programs. Its specialist, tech‑enabled operating model and coverage breadth across 120+ instrument types support competitive positioning with sophisticated managers.
Market Expansion: The company expanded its footprint with a new operations office in Gdańsk and signaled further build‑out with additional hiring plans in Dublin. Active recruiting across regions through 2025–2026 and an expanded office map indicate ongoing geographic growth.
Customer Loyalty & Retention: The firm cites very high client retention alongside growth to 700+ billion in AuA, pointing to durable relationships with demanding alternative‑asset clients. Historical top marks in administrator honors reinforce a reputation that supports stickiness among hedge‑fund and private‑markets managers.



