

Top Health Tech Companies in Boston, MA (555)

Click Therapeutics, Inc., develops, validates, and commercializes software as prescription medical treatments for people with unmet medical needs. As a leading innovator of Digital Therapeutics™, Click delivers accessible, clinically proven, FDA-regulated prescription treatments to the smartphone in your hand. Click’s treatments are defined by a commitment to applying technical and scientific rigor and patient-centric design to the development process. This...
Click Therapeutics's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Recent financing includes a $50 million Series D anchored by Boehringer Ingelheim, following a Series C in 2025 and prior debt financing, indicating sustained access to strategic capital. The transfer of CT-155 commercialization responsibility alongside dedicated commercial funding further underscores capital support aligned with near-term growth plans.
Strategic Partnerships: Collaborations with major pharmaceutical companies such as Otsuka and Boehringer Ingelheim, alongside agreements with Indivior and Ultrahuman, reflect deepening partner engagement in development and commercialization. These alliances have produced FDA-authorized products and structured milestone and royalty pathways that reinforce external validation.
Product Line Growth: Multiple FDA authorizations (Rejoyn for MDD and CT-132 for migraine), the acquisition of AspyreRx, and an expanded pipeline spanning psychiatry, neurology, and cardiometabolic disease point to a broader, more mature portfolio. Positive Phase 3 results and commercialization preparations for CT-155 add momentum to this expansion.
SOPHiA GENETICS (Nasdaq: SOPH) is a healthcare technology company dedicated to establishing the practice of data-driven medicine as the standard of care and for life sciences research. It is the creator of the SOPHiA DDM™ Platform, a cloud-based SaaS platform capable of analyzing data and generating insights from complex multimodal data sets and different diagnostic modalities. The SOPHiA DDM™ Platform...

SOPHiA GENETICS's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 19% in 2025 and accelerated in 2026 with 22% year-over-year growth in Q1 and 27% in Q2, while first-half 2026 revenue rose 25% year over year. Management raised full-year 2026 guidance to $94–96M, implying roughly 22–24% growth.
Customer Loyalty & Retention: Net Dollar Retention reached 117% in Q1 2026, indicating expanding spend from existing accounts after churn. Core genomics customers rose to 537 as of March 31, 2026, with record new customer additions in 2025.
Market Expansion: Geographic momentum is evident with Q1 2026 analysis volume up 28% in the U.S. and 31% in APAC, and EMEA revenue up 30%. Platform usage set records (e.g., 108,000 analyses in Q1 and 115,000 in Q2), with liquid biopsy volumes growing sharply.

Arcadia is a leading healthcare data analytics platform that helps payers and providers turn complexdata into actionable insights. In turn, payers and providers can focus on what matters most — whether that’s patient outcomes, operational efficiencies, or financial performance. Arcadia partners with many of the nation’s top healthcare organizations and empowers its teams to drive real-world impact through innovation, collaboration,...

Arcadia's Top Stability & Growth Strengths
Strong Revenue Growth: Inc. 5000 recognitions cite 82% and 72% three-year growth, and investor disclosures note meaningful 2025 revenue scale, indicating sustained multi-year expansion. While precise YoY rates aren’t public, repeated list appearances and disclosed scale point to continued momentum.
Investor Backing & Capital Strength: Nordic Capital became the majority owner in 2025 to support the next phase of growth, expansion, and platform investment. Additional financing and stated plans for strategic acquisitions further reinforce access to growth capital.
Market Expansion: Customer and data footprint expanded to 170M+ patient records across 200+ provider/payer organizations, with more than 2.25M value-based lives added in 2024. Management and media describe ambitions for further expansion via M&A and potential moves beyond the U.S.
Who We Are Chewy is where pet parents find everything they need for life with pets, from food to fun to pharmacy. We make pet care easier, more informed, and more joyful through fast, reliable delivery and award-winning 24/7 Customer Care, including access to pet health support when it’s needed. Founded in 2011, Chewy combines the convenience of online shopping with...

Chewy's Top Stability & Growth Strengths
Customer Loyalty & Retention: Autoship accounts for the vast majority of sales (over four-fifths) and is growing faster than total revenue, indicating a sticky, recurring base and higher retention. Evidence includes Autoship representing ~83% of FY2025 net sales and ~84.6% in Q2 FY2026 with high single‑digit to double‑digit growth.
Profitability: Operating metrics show expanding earnings power, with adjusted EBITDA up materially and margins improving alongside strong free cash flow. Observations include FY2025 adjusted EBITDA growth of ~26% with margin expansion and additional year‑over‑year gains reported in 1H FY2026.
Strong Market Position & Advantage: Chewy is characterized as the largest U.S. pet e‑tailer and a leading online pet‑supplies platform by GMV and digital presence, underpinning durable scale advantages. Multiple summaries highlight leadership in online pet retail, substantial Autoship penetration, and strong digital search share versus specialty peers.

Cohere Health’s clinical intelligence platform and agentic AI-powered solutions connect health plans’ strategic goals and providers’ needs, optimizing the speed, cost, and quality of care. With an enterprise approach that streamlines payer-provider decision-making across the care continuum–including policy, prior authorization, payment accuracy, and more–the company improves collaboration and reduces burden, resulting in up to 8x ROI and 94% provider satisfaction....

Cohere Health's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported as expanding rapidly, with more than 60% year-over-year growth in committed ARR in 2024. External recognitions like Deloitte Technology Fast 500 and repeat Inc. 5000 placements point to sustained multi-year momentum.
Market Expansion: New health plan partnerships and an increase to 17 health plans by 2026, alongside 12 million annual prior authorizations and 25M covered lives, indicate a widening commercial footprint. Integrations such as Epic’s Payer Platform and expanded relationships with national and regional plans reinforce adoption.
Investor Backing & Capital Strength: A $90 million Series C in 2025 brought total funding to roughly $200 million. Successive raises and participation from prominent investors suggest ample capital to support scaling.
We bring together one of the world’s largest libraries of multimodal clinical and molecular data with a robust suite of AI tools to help physicians personalize care in real time, connect patients with therapies and clinical trials, and enable partners to accelerate discovery and development of new treatments. With ~8 million de-identified research records and 350+ petabytes of data, Tempus partners...
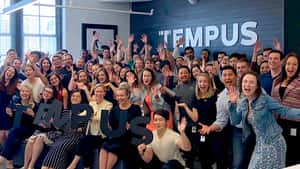
Tempus AI's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at double-digit rates across recent periods, and management has increased full-year guidance, underscoring continued momentum. Growth is visible in both recent quarters and the prior year, indicating sustained top-line expansion.
Diversified Revenue Streams: Both Diagnostics and Data & Applications are expanding, with data-licensing/Insights activity increasing alongside clinical testing volumes. This mix reduces reliance on a single line of business and supports multiple growth vectors.
Strategic Partnerships: Collaborations with major biopharmaceutical companies and broader rollouts of platforms such as Next signal expanding commercial reach. Announced initiatives like a large whole‑genome dataset and work with firms including Merck reinforce external demand for the platform.
Biotechnology is rewriting life as we know it, from the medicines we take, to the crops we grow, and the household goods that we rely on every day. But moving at the new speed of science requires better technology. Benchling’s mission is to unlock the power of biotechnology. The world’s most innovative biotech companies use Benchling’s R&D Cloud to power the...
Benchling's Top Stability & Growth Strengths
Strong Market Position & Advantage: Adoption spans 1,300+ biotechnology organizations with usage reported across more than half of the top 50 biopharma companies, signaling durable positioning in life‑sciences R&D software. Multiple sources characterize the platform as a leading life‑sciences R&D cloud used by both startups and major enterprises.
Product Line Growth: The company continues to launch and expand major offerings, including Benchling AI, antibody‑discovery capabilities, automation/analysis tools, and extensions into new scientific workflows such as small‑molecule chemistry. Acquisitions like PipeBio further broaden capability depth in biologics and related R&D domains.
Innovation-Driven Growth: AI is a clear growth vector, with reports that 500 biotech companies used Benchling AI in its first year and the product subsequently reached general availability. Team acquisitions (e.g., ReSync Bio and Sphinx Bio) and partnerships (e.g., with Anthropic) underscore a deliberate push to embed advanced models into scientific workflows.
For more than two decades, Imprivata has been redefining how life- and mission-critical industries secure and manage digital identities. We empower healthcare and enterprise organizations to enable fast, compliant, and secure access to technology—allowing clinicians and staff to stay focused on what matters most: patient care and operational excellence. Our digital identity platform is purpose-built for complex environments where every second...

Imprivata's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as sizable and growing rapidly, with independent reporting and credit analyses pointing to continued double‑digit expansion. ARR and ACV are characterized as increasing consistently since 2022.
Customer Loyalty & Retention: Retention is depicted as very high, with consistent expansion within existing accounts that supports sustained recurring revenue growth. Commentary highlights strong share‑of‑wallet gains and durable renewals across healthcare customers.
Product Line Growth: The portfolio has broadened through repeated acquisitions (e.g., SecureLink, Verosint) and new capabilities such as passwordless authentication and agentic identity management. These moves signal active investment to expand addressable use cases and deepen the platform.
Founded in 2013 with a vision to eliminate the need for single-use bottles and cans, Bevi is redefining how beverages are delivered in commercial spaces. Best known for its Smart Water Cooler®, Bevi has grown into the leading connected beverage platform, combining hardware, data, and beverage innovation to deliver still, sparkling, flavored, and enhanced drinks on demand. Powered by real-time...

Bevi's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have surpassed the $100 million annual mark with continued year-over-year gains. Feedback suggests momentum is reinforced by growth in newer verticals such as education and hospitality.
Market Expansion: The company extended its footprint from North America into the UK and Ireland and broadened placements beyond offices into campuses, hotels, gyms, warehouses, and other venues, while scaling to more than 6,000 customers. Feedback suggests international entry and vertical diversification are driving a larger installed base and usage milestones such as surpassing one billion single-use containers avoided.
Product Line Growth: The offering advanced from smart water coolers to a connected beverage platform, adding functional enhancements and a better-for-you soda line alongside new countertop hardware. Feedback suggests the expanded menu increases relevance across more locations and upsell potential within existing accounts.

InterSystems builds the software that makes complex systems work—reliably, securely, and at scale. For more than 45 years, we’ve been the information engine behind some of the world’s most mission-critical applications in healthcare, government, and business. Our data management, integration, and analytics technologies help organizations connect disparate systems, turn data into insight, and deliver better outcomes. From enabling interoperable healthcare and...

InterSystems's Top Stability & Growth Strengths
Profitability: The company is described as privately held, profitable, and debt-free, indicating a solid financial base. This positioning supports continued investment without reliance on external financing.
Strong Revenue Growth: Revenue is reported above $1 billion with indications of year-over-year increases into 2024 and sustained scale into FY2025, while cloud segments are noted as expanding strongly. These signals point to ongoing top-line momentum.
Market Expansion: Operations span 28 countries with 38 offices serving customers in 80+ countries, alongside recent moves such as a dedicated public-sector subsidiary and added international presence. This footprint suggests continued geographic and channel growth.
Babylist is the trusted platform for millions of growing families. For over a decade, Babylist has been the technology solution for expecting parents and the community that supports them, expanding from baby registry into a full-service platform that helps parents make decisions with confidence, stay connected, and build happy and healthy families. Every year Babylist helps over 9M people make...
Babylist's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have surpassed $750 million in 2025, up 45% year over year, with momentum indicated into 2026. More than 10 million people made purchases through the platform in 2025, aligning with the topline expansion.
Profitability: The company recorded its eighth consecutive profitable year in 2025, indicating expansion with positive economics. This profitability streak accompanies the recent revenue step-up.
Diversified Revenue Streams: Growth extends beyond the core registry, with Health revenue up 64% and Media up 35% in 2025. Physical showrooms, a large fulfillment center, and media/content initiatives further broaden monetization.
AcuityMD is the intelligence platform for the MedTech industry. AcuityMD's AI platform is designed to help medical technology companies identify target markets, surface top opportunities, and grow their businesses. With customers ranging from pre-commercial to enterprise, AcuityMD is committed to delivering the right insights so companies can understand where and how to sell faster to accelerate the adoption of medical...
AcuityMD's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have expanded dramatically over a recent three-year period, earning recognition on a leading high-growth list. Feedback suggests this reflects substantial commercial traction rather than growth based solely on financing.
Strong Market Position & Advantage: Customer adoption spans 500+ MedTech companies, including deep penetration among the largest enterprises (e.g., 16 of the top 20). Feedback suggests this breadth and upmarket presence signal durable positioning within its niche.
Investor Backing & Capital Strength: Capital raised has surpassed $160M with a recent late-stage round and a valuation near the unicorn threshold. Feedback suggests this funding base supports continued product expansion, AI initiatives, and go-to-market scale.
ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Strong Hiring & Retention: Hiring and headcount are expanding, with disclosures of 15,000+ global employees, thousands of new hires, and third‑party estimates indicating continued workforce growth. Available evidence also points to active internal mobility and a recent increase in active job postings.
Market Expansion: Geographic and client footprints are broadening, with 40+ offices and 1,700+ customers across 170+ countries alongside concrete investments in new and expanded locations such as Hyderabad and Kingston. These moves indicate scaling delivery capacity in major capability centers and new regions.
Innovation-Driven Growth: The offering mix is shifting toward AI, data, technology, and platforms, including proprietary solutions and product capabilities. Strategic moves such as Salesforce-focused acquisitions and collaborations, plus a Tulip solution partnership, extend capabilities beyond traditional consulting.
Schrödinger is a leading provider of advanced molecular simulations and enterprise software solutions and services for pharmaceutical, biotechnology, and materials science research. The predictive power of Schrödinger's software allows scientists to accelerate their research and development, reduce research costs, and make novel discoveries.
Schrödinger, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate total revenue increased year over year in 2025 and continued to rise in the latest reported quarter. Guidance and quarterly updates point to ongoing top-line expansion even as mix shifts occur.
Resilient & Sustainable Growth: Underlying annual contract value expanded and accelerated in 2026, with management indicating continued growth despite the transition to hosted licensing. This suggests the core subscription base is strengthening even when reported revenue timing varies.
Diversified Revenue Streams: Growth is visible in both the software business and the milestone-driven drug discovery segment. The latter stepped up meaningfully in recent periods, complementing steady software momentum.
EliseAI builds vertical AI agents for housing and healthcare — sectors that together make up nearly 40% of household spending. These agents automate high-volume workflows like leasing, maintenance, renewals, and patient intake, helping organizations cut costs, improve efficiency, and deliver better experiences. How does it work? EliseAI integrates directly into operational workflows: Housing: Manages leasing, maintenance, renewals, billing, and resident communication. Healthcare: Handles intake,...
EliseAI's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have surpassed $200M by June 2026 after crossing $100M in early 2025, with five consecutive years of 100% year-over-year growth. This consistent doubling signals rapid scaling at substantial revenue levels.
Investor Backing & Capital Strength: Funding rounds include $75M in 2024 at a valuation above $1B and a $250M Series E in 2025 at a reported $2.2B, with total capital raised cited at $400M+. Such late-stage financing and rising valuations indicate robust access to growth capital.
Strong Market Position & Advantage: Adoption is described as reaching roughly 1 in 6 U.S. apartments, with deep penetration among large property managers and hundreds of operators. Expansion into healthcare and notable distribution relationships have broadened its commercial footprint.
Formation Bio is a tech-driven pharma company differentiated by radically more efficient drug development. Formation Bio has built a technology platform that optimizes all aspects of drug development, enabling more efficient trial design, faster trial completion, and higher quality trial data capture. Formation Bio acquires clinical-stage drugs from pharma and biotech and develops them faster and more efficiently, unlocking greater...

Formation Bio's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raising has accelerated, including a $372M Series D in 2024 with total funding reported in the hundreds of millions to expand the pipeline and AI platform. Valuation has stepped up from roughly $1.04B (2021) to about $1.48B post‑money (2024), signaling strengthened private‑market positioning.
Strategic Partnerships: Partnerships are expanding, highlighted by a collaboration with Sanofi and OpenAI to build AI software for drug development and increased business‑development capacity via Entrepreneurs in Residence. Engagements with large pharma partners, including Sanofi, underscore growing external validation and deal flow.
Product Line Growth: The pipeline is broadening through multiple in‑licenses—such as an anti‑CD226 program, a CNS‑penetrant TYK2 inhibitor, and a miR‑124 activator—and progression to first‑in‑human dosing of BLKR201 in 2026. Stated plans to reach 10–15 assets over 3–5 years align with recent portfolio expansion and clinical advancement.

Laudio empowers healthcare leaders to drive large-scale change through everyday human actions. Our platform streamlines workflows for frontline leaders, strengthens interpersonal connections, and aligns C-suite objectives with frontline efforts, enhancing leader efficiency, employee engagement, and patient experience. Laudio makes it possible for patients, frontline workers, and health system leaders to thrive together. Discover how at www.laudio.com.

Laudio's Top Stability & Growth Strengths
Market Expansion: Customer reach is expanding across large U.S. health systems, with cited growth from 14+ systems in 2022 to 20+ more recently and examples of system‑wide expansions (e.g., Northwell Health). This footprint is described as covering thousands of leaders and hundreds of thousands of frontline staff, indicating broader adoption.
Product Line Growth: The platform has added meaningful capabilities, including the 2025 launch of AI‑powered Performance Insights and modules spanning engagement, performance/development, overtime/attendance, and patient rounding/audits. This suggests a strategy to deepen value and expand use cases within existing customers.
Strong Revenue Growth: Historical revenue expansion is externally signaled by Laudio’s #95 placement on Deloitte’s 2023 Technology Fast 500. This recognition aligns with the broader picture of rapid past scaling.
At WHOOP, we’re on a mission to unlock human performance. WHOOP empowers members to perform at a higher level through a deeper understanding of their bodies and daily lives. Our wearable device and performance optimization platform has been adopted by many of the world's greatest athletes and consumers alike.

WHOOP's Top Stability & Growth Strengths
Strong Revenue Growth: Bookings are reported to have grown 103% year over year in 2025, exiting at a roughly $1.1B annualized run rate, indicating rapid top-line momentum. Additional signals such as sustained wholesale growth reinforce that commercial scale is accelerating.
Healthy Cash Flow: Operations are described as cash-flow positive in 2025 while growth accelerated, suggesting improving financial sustainability alongside expansion. This combination points to scaling that is not purely subsidized by burn.
Investor Backing & Capital Strength: A $575M Series G at a $10.1B valuation underscores substantial access to capital and confidence from prominent investors. This financing is framed as enabling continued international expansion and hiring.
As a leading health technology company, it is our purpose to improve people’s health and well-being through meaningful innovation. Our goal is to improve 2.5 billion lives per year by 2030. We're always looking for ways to make life better – not only for our customers, but also for everyone working here. That's why we're taking steps to create an...
Philips's Top Stability & Growth Strengths
Strong Market Position & Advantage: Philips is positioned as a leader across multiple health-technology categories, with cited top standings in interventional systems, PACS, monitoring, and a large installed base that supports ongoing competitiveness.
Profitability: Margins are described as improving, with adjusted EBITA expanding through 2025 and management targeting further margin improvement into the mid-teens by 2028.
Innovation-Driven Growth: Innovation capacity is reinforced through repeated recognition as a top global innovator, sustained R&D intensity, and an innovation roadmap expected to contribute meaningfully to growth and margin improvement.

Ipsen is a French leading global mid-size biopharmaceutical company headquartered in Paris, France focusing its efforts where unmet medical needs are greatest. Ipsen develops and commercializes innovative medicines in three key therapeutic areas - Oncology, Rare Disease and Neuroscience. We have over 5000 employees worldwide and our medicines are registered in more than 100 countries, with direct commercial presence in...
Ipsen's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show double-digit growth at constant exchange rates in 2024 and 2025 with an accelerated start in Q1 2026, and guidance indicates continued expansion in 2026. This momentum spans all three therapeutic areas rather than a single product.
Profitability: Disclosures highlight expanding core operating margins above the mid-30s and rising core operating income. Guidance continues to target strong margins alongside growth.
Diversified Revenue Streams: Recent updates indicate contributions from Oncology, Rare Disease, and Neuroscience, with products excluding Somatuline growing strongly and rare disease accelerating. Strategic acquisitions and partnerships have broadened the base beyond any single legacy brand.



