

Top IT Companies in Boston, MA (536)
As the world’s largest asset manager, BlackRock partners with investors around the globe to help them (and those on whose behalf they invest) plan for life’s most important goals – like retirement, home ownership and their children’s education. Our clients range from governments, foundations and other large institutions to those investing on behalf of individuals, including firefighters, nurses, teachers and...

BlackRock's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in 2025 and accelerated further in early 2026, with adjusted operating income also rising. This points to broad-based top-line momentum beyond a single period.
Strong Market Position & Advantage: The company is characterized as the world’s largest asset manager with record-high assets under management and leading ETF scale. This scale advantage underpins continued client inflows and platform reach.
Diversified Revenue Streams: Growth is coming from multiple engines, including iShares ETFs, active strategies, private markets, and technology services such as Aladdin, alongside newer digital-asset offerings. This breadth reduces reliance on any single product line.
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Results show sustained low- to mid‑20s year‑over‑year expansion, including roughly 23% in Q2 2026 and 24% for full‑year 2025. Guidance points to continued double‑digit growth in recurring gross profit.
Profitability: Financial disclosures indicate rising GAAP profitability, with Q2 2026 net income increasing to about $154 million and adjusted EBITDA stepping up alongside raised full‑year targets. Profit growth is occurring in tandem with expanding scale across ARR, locations, and GPV.
Strong Market Position & Advantage: Evidence characterizes the company as a leading U.S. restaurant‑focused platform with approximately 180,000 locations, record quarterly net adds, and notable enterprise wins and partnerships. Scale in locations and GPV reinforces competitive positioning within restaurant technology and payments.
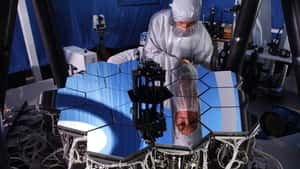
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.

Arcadia is a leading healthcare data analytics platform that helps payers and providers turn complexdata into actionable insights. In turn, payers and providers can focus on what matters most — whether that’s patient outcomes, operational efficiencies, or financial performance. Arcadia partners with many of the nation’s top healthcare organizations and empowers its teams to drive real-world impact through innovation, collaboration,...

Arcadia's Top Stability & Growth Strengths
Strong Revenue Growth: Inc. 5000 recognitions cite 82% and 72% three-year growth, and investor disclosures note meaningful 2025 revenue scale, indicating sustained multi-year expansion. While precise YoY rates aren’t public, repeated list appearances and disclosed scale point to continued momentum.
Investor Backing & Capital Strength: Nordic Capital became the majority owner in 2025 to support the next phase of growth, expansion, and platform investment. Additional financing and stated plans for strategic acquisitions further reinforce access to growth capital.
Market Expansion: Customer and data footprint expanded to 170M+ patient records across 200+ provider/payer organizations, with more than 2.25M value-based lives added in 2024. Management and media describe ambitions for further expansion via M&A and potential moves beyond the U.S.
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding at strong double‑digit rates across recent quarters and the latest fiscal year, with cloud revenue and ARR also rising. Investor materials and quarterly updates highlight consistent momentum rather than a one‑off spike.
Strong Market Position & Advantage: Independent analyst recognitions position the company as a Leader across multiple core categories, and it serves a very large, global customer base including much of the Fortune 500. This broad market presence supports pricing power, cross‑sell, and durable demand.
Innovation-Driven Growth: Cloud migrations and newly introduced AI capabilities are cited as meaningful tailwinds for adoption and expansion. Product enhancements and platform integrations are associated with larger enterprise deals and a growing backlog of committed revenue.
Together, we turn ambition into action. For more than three decades, Citadel has captured undiscovered market opportunities in markets around the world by empowering extraordinary people to pursue their best and boldest ideas. We strive to identify the highest and best uses of capital to generate superior long-term returns for the world’s preeminent public and private institutions.
Citadel's Top Stability & Growth Strengths
Profitability: Investment performance is described as exceptional over multiple years, with LCH citing record cumulative net gains and annual investor profits including a record ~$16B in 2022 and further multibillion-dollar gains in 2023–2024. This track record positions the firm at or near the top of cumulative profitability rankings.
Strong Revenue Growth: Trading revenue at the affiliated market maker rose sharply, reaching a record ~$12.2B in 2025 and accelerating further with multi‑billion‑dollar quarters in 2026. This momentum indicates expanding top‑line scale alongside broader business activity.
Market Expansion: The geographic footprint is widening with Dubai slated as the 18th city, a growing London hub, and new or expanded sites such as New York, Miami, and Amsterdam. International hiring and build‑outs across Asia and Europe further reinforce expansion into additional markets.
At 3Play Media, we’re transforming the way organizations approach video accessibility and localization—making it faster, easier, and more reliable to reach every viewer. From captions and subtitles to audio descriptions and dubs, our platform streamlines workflows that once took days into just a few clicks. We support thousands of customers across media & entertainment, education, enterprise, and sports—helping them expand...

3Play Media's Top Stability & Growth Strengths
Product Line Growth: The company has broadened offerings beyond captioning into transcription, live captioning, audio description, localization, and AI-enabled dubbing, including new products like Pulse and a YouTube-focused AI dubbing solution. Company-reported usage for dubbing (30+ million hours watched) indicates meaningful adoption of newer products.
Market Expansion: Acquisitions of Captionmax and National Captioning Canada expanded capabilities and geographic reach into Canada, with subsequent integration under the 3Play brand. A 2025 rebrand and creator-focused launches signal entry into new segments and international localization markets.
Investor Backing & Capital Strength: A majority investment from Riverside Partners and the 2025 addition of a CFO, alongside promotions to a Chief Growth Officer and CTO, indicate financial and organizational readiness for scale. Active openings in customer success, sales, and delivery roles further suggest continued investment in growth operations.
Coupa is a global technology company that helps businesses run smarter by connecting all the ways they spend money — from procurement and expenses to payments and supply chain decisions — in one intelligent platform. In simple terms, Coupa gives organizations the visibility and control they need to make better financial choices, reduce waste, and drive real impact. It’s where...
Coupa's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as reaching a record level in Q4 FY2026, with continued ARR growth and earlier double‑digit bookings gains indicating ongoing top‑line momentum.
Customer Loyalty & Retention: Renewals and expansions are emphasized, with more than 1,300 organizations renewing or expanding in FY2026. This points to durable engagement within the installed base.
Innovation-Driven Growth: Product advances such as AI agents and new applications, alongside acquisitions like Rossum and Tonkean, are expanding the platform’s capabilities. These moves are linked to increased adoption and expansion activity.

Workhuman® is helping companies meet today’s biggest human capital challenges - including unprecedented turnover, employee engagement, hybrid work environments, and DE&I - through the Workhuman Cloud®, a secure SaaS platform that provides the industry’s best-in-class Social Recognition® solution. Co-Headquartered in Dublin, Ireland, and Framingham, Massachusetts, USA, Workhuman has been pioneering the human workplace to improve the employee experience at work,...

Workhuman's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as scaling to roughly $1.2B by 2025 from materially lower prior figures, indicating continued top-line momentum. Media-reported milestones and earlier disclosures depict a multi‑year climb in business scale.
Profitability: Sustained profitability over many years is highlighted alongside billion‑dollar revenue, signaling a stable financial base. This combination suggests capacity to invest in product and market initiatives without sacrificing stability.
Market Expansion: Platform adoption has reached about 8 million users across 180+ countries with 100+ million recognition moments, pointing to broader geographic and customer reach. Growth in users since 2023 reinforces ongoing international footprint expansion.

.png)
At ReversingLabs, we are providing the world’s largest threat intelligence repository to protect software development and power advanced security solutions, keeping the most advanced cybersecurity organizations and Fortune 500 enterprises informed and ahead of the threats. Our software supply chain security and threat intelligence solutions have become essential to advancing enterprise cybersecurity maturity globally. Notable breaches such as SolarWinds, CircleCI and...
ReversingLabs's Top Stability & Growth Strengths
Product Line Growth: Spectra Assure’s customer base is described as having grown more than 150% in 2024, with the company again stating more than 150% growth since its 2024 launch into 2025. Platform activity also expanded, including a 48% year-over-year increase in identified malicious files.
Strategic Partnerships: Routes to market are broadening through initiatives such as the AWS ISV Accelerate Program, an expanded partner program, and public‑sector marketplace “Awardable” listings. The company also highlights that its data is used by more than 65 major security vendors, indicating ecosystem reach.
Investor Backing & Capital Strength: Capital availability appears solid, with approximately $120 million reported across multiple funding events, including a 2024 round. An investment led by Crosspoint Capital Partners is described as intended to accelerate growth in software supply‑chain security.
Robin is the leading AI platform for workplace operations. Since 2014, we’ve empowered people to do their best work by building tech solutions that fuel vibrant workplace experiences - allowing you to plan, manage and use your office in an intelligent way. With the leading desk and room booking software, the industry's first AI agent and our powerful workplace analytics,...
Robin's Top Stability & Growth Strengths
Strong Market Position & Advantage: Gartner included Robin as a Leader in its 2026 Magic Quadrant for Workplace Experience Applications, indicating strong competitive standing in this category. The company’s statement that it serves thousands of organizations further reflects broad market presence.
Market Expansion: The July 2026 launch on Google Cloud Marketplace opens a new procurement path through existing Google Cloud commitments for enterprise buyers. This move represents a meaningful extension of distribution and market access.
Product Line Growth: The platform has expanded from room/desk booking into a broader workplace-operations suite covering visitor management, space planning, analytics, and AI. 2026 updates such as a natural-language workplace agent, CAD-to-map functionality, and move-management tools illustrate continued breadth.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
For more than two decades, Imprivata has been redefining how life- and mission-critical industries secure and manage digital identities. We empower healthcare and enterprise organizations to enable fast, compliant, and secure access to technology—allowing clinicians and staff to stay focused on what matters most: patient care and operational excellence. Our digital identity platform is purpose-built for complex environments where every second...

Imprivata's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as sizable and growing rapidly, with independent reporting and credit analyses pointing to continued double‑digit expansion. ARR and ACV are characterized as increasing consistently since 2022.
Customer Loyalty & Retention: Retention is depicted as very high, with consistent expansion within existing accounts that supports sustained recurring revenue growth. Commentary highlights strong share‑of‑wallet gains and durable renewals across healthcare customers.
Product Line Growth: The portfolio has broadened through repeated acquisitions (e.g., SecureLink, Verosint) and new capabilities such as passwordless authentication and agentic identity management. These moves signal active investment to expand addressable use cases and deepen the platform.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR moved from surpassing $300M in June 2025 to exceeding $400M by May 2026, indicating a substantial year-over-year increase. The company also reported a 36% five-year organic CAGR in 2024, underscoring sustained momentum.
Product Line Growth: Edwin AI recurring revenue is reported to be growing around 200% year over year and contributing about one-third of total bookings. The December 2025 Catchpoint acquisition expanded capabilities into internet performance and digital experience monitoring.
Market Expansion: Larger enterprise accounts grew more than 25% year over year in 2025 and the company cited 700+ enterprise customers by late 2025. More than 30% of new customers came from outside the U.S., indicating ongoing international expansion.
Snyk, the leader in secure AI software development, empowers organizations to build fast and stay secure by unleashing developer productivity and reducing business risk. The company’s AI Trust Platform seamlessly integrates into developer and security workflows to accelerate secure software delivery in the AI Era. Snyk delivers trusted, actionable insights and automated remediation, enabling modern organizations to innovate without limits....
Snyk's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue and ARR continued to rise, with ARR surpassing $300M by 2025 and revenue increasing in 2024. Feedback suggests growth has moderated from earlier hypergrowth into a steadier, efficiency‑focused trajectory while the customer base expanded to 4,500+.
Product Line Growth: Snyk Code reached $100M in ARR and newer offerings such as DAST and AI‑focused products (e.g., Evo) showed strong momentum. These developments indicate the platform is extending beyond its original core into additional security categories.
Market Expansion: Enterprise adoption intensified, with that segment driving a large share of new additions and AI security opening fresh routes to demand. Customer counts grew materially from 2024 into 2025, signaling broader market reach.
As part of the Central bank of the United States, the Boston Fed works to promote sound growth and financial stability in New England and the nation. We contribute to communities, the region, and the nation by conducting economic research, participating in monetary policy-making, supervising certain financial institutions, providing financial services and payments, playing a leadership role in the payments...
Federal Reserve Bank of Boston's Top Stability & Growth Strengths
Strong Hiring & Retention: Staffing is budgeted to rise from 1,276 FTE in 2024 to 1,321 in 2025, and the Bank reported 125 new hires in 2024. These data point to continued investment in personnel to support core responsibilities.
Future-Ready Strategy: Operating resources are set to expand, with a 2025 budget of $460.0M versus $431.0M in 2024 actuals, alongside stepped-up technology and facilities investments. The institution emphasizes modernization of payments infrastructure (e.g., FedNow) and systems as part of this plan.
Innovation-Driven Growth: Leadership in instant payments (FedNow), ongoing payments initiatives, and active research series through 2026 highlight expansion anchored in innovation. New structures such as the First District Payments Advisory Council reinforce its role in evolving the payments landscape.

Immersive, the leader in people-centric cyber resilience, helps organizations continuously prove and improve its ability to prevent and respond to cyber threats. Tailored to individual roles, our approach ensures organizations are always ready for an ever-evolving threat landscape, including the opportunities and challenges posed by AI. With a relentless focus on evidence, Immersive provides unmatched visibility into an organization's cyber...

Immersive's Top Stability & Growth Strengths
Strong Revenue Growth: Company filings indicate group turnover rose steadily from 2020 through 2024, with 2024 revenue higher than 2023 and materially above 2020 levels.
Investor Backing & Capital Strength: Funding rounds in 2021–2022 and an additional 2024 investment show continued support from major institutional investors and access to capital.
Market Expansion: Company materials describe service to 400+ organizations, adoption among Fortune 100 enterprises, and operations across the US, UK, and EMEA, indicating broader market reach.
It's simple, at DraftKings, we believe life is more fun when you're in on the action. For that reason, we’re committed to responsibly creating the world’s favorite games and betting experiences. We’re developing the most innovative and entertaining real money products and offers; to forever transform how people experience sports; to be a fully vertically integrated sports betting operator. It's...

DraftKings's Top Stability & Growth Strengths
Strong Revenue Growth: Reported results show revenue rising from $3.67B (2023) to $4.77B (2024) to $6.05B (2025), with early 2026 revenue and guidance pointing to further gains. Q1 2026 continued to grow year over year, alongside expanding sportsbook handle and average monthly payers.
Profitability: Reported results show Adjusted EBITDA improving from $181M (2024) to $620M (2025) and a shift to positive GAAP net income in 2025. Guidance indicates substantial Adjusted EBITDA for 2026.
Product Line Growth: Company disclosures describe rising iGaming revenue in 2025 and the launch of new offerings like Predictions and a consolidated “super app.” These additions broaden the business beyond traditional sportsbook and DFS.
Since 2012, Mirakl has been pioneering the platform economy, empowering retail and B2B enterprises with the most advanced, secure and scalable technology to digitize and expand product assortment through marketplace and dropship, improve efficiency in supplier catalog management and payments, personalize shopping experiences, and boost profits through retail media. Mirakl is trusted by Macy’s, Saks, Henry Schein, The Knot, 1800-Flowers, Best...

Mirakl's Top Stability & Growth Strengths
Strong Revenue Growth: ARR increased from $177M in 2024 to $218M in 2025, with reported ARR roughly doubling since 2021. Platform activity also expanded as GMV rose from $11.2B to about $14.6–$15B over the same period.
Profitability: The group was profitable throughout 2025, following earlier profitability in the core Platform business. This progression indicates improving operating leverage alongside continued expansion.
Diversified Revenue Streams: Newer products are contributing incremental revenue, with Mirakl Connect generating about $11.7M ARR in under a year and Mirakl Ads seeing a sharp rise in ad spend in 2025. Customer additions (45 global enterprises in 2025) and launches across marketplace and dropship broaden the commercial base.
HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
HERE Technologies's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with automakers such as Hyundai AutoEver, Lotus, and Amap, alongside cloud collaborations like AWS and ecosystem ties with Esri, continue to expand. These relationships appear to deepen distribution and integration across automotive and enterprise use cases.
Innovation-Driven Growth: The portfolio is expanding into AI, software-defined vehicles, ADAS, autonomous driving, and logistics, with launches such as HERE SDK updates and Location Reasoning. This trajectory indicates increasing focus on higher-value, future-oriented offerings.
Strong Market Position & Advantage: Independent analyst indices (Omdia and Counterpoint) repeatedly place the company at the top of location-platform rankings, and installed vehicle use rose from 222M to 238M. These signals point to sustained competitive standing and broad automotive adoption.



